Thinking About Using Your 401(k) To Buy a Home? Read This First.
If you are hoping to buy a home in Hinesville, Fort Stewart, or somewhere else in Southeast Georgia, you may have wondered whether your retirement savings could help cover the upfront costs.
With home prices, mortgage rates, and other purchasing costs all playing a role in affordability, it is understandable that buyers are exploring different ways to put together the funds they need.
But before you tap into your 401(k), there is an important question to ask:
What could use that money today mean for your financial future?
Using retirement savings to help purchase a home can be an option in some circumstances, but it comes with important considerations. Before making a decision, it is worth reviewing all of your options and speaking with a qualified financial, tax, or retirement professional.
Why Using Your 401(k) Can Be Tempting
A 401(k) account can look like a possible source of funds when you are trying to save for a down payment or closing costs.
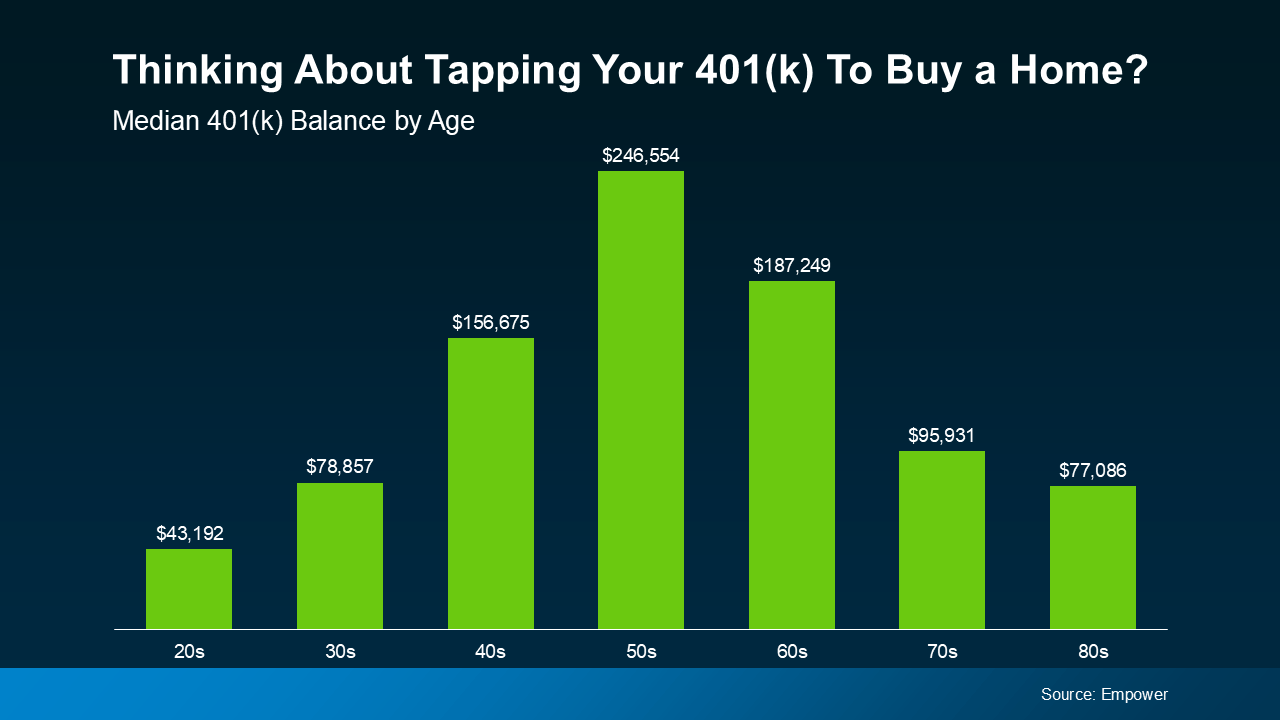
But retirement savings are designed to support you in the future.
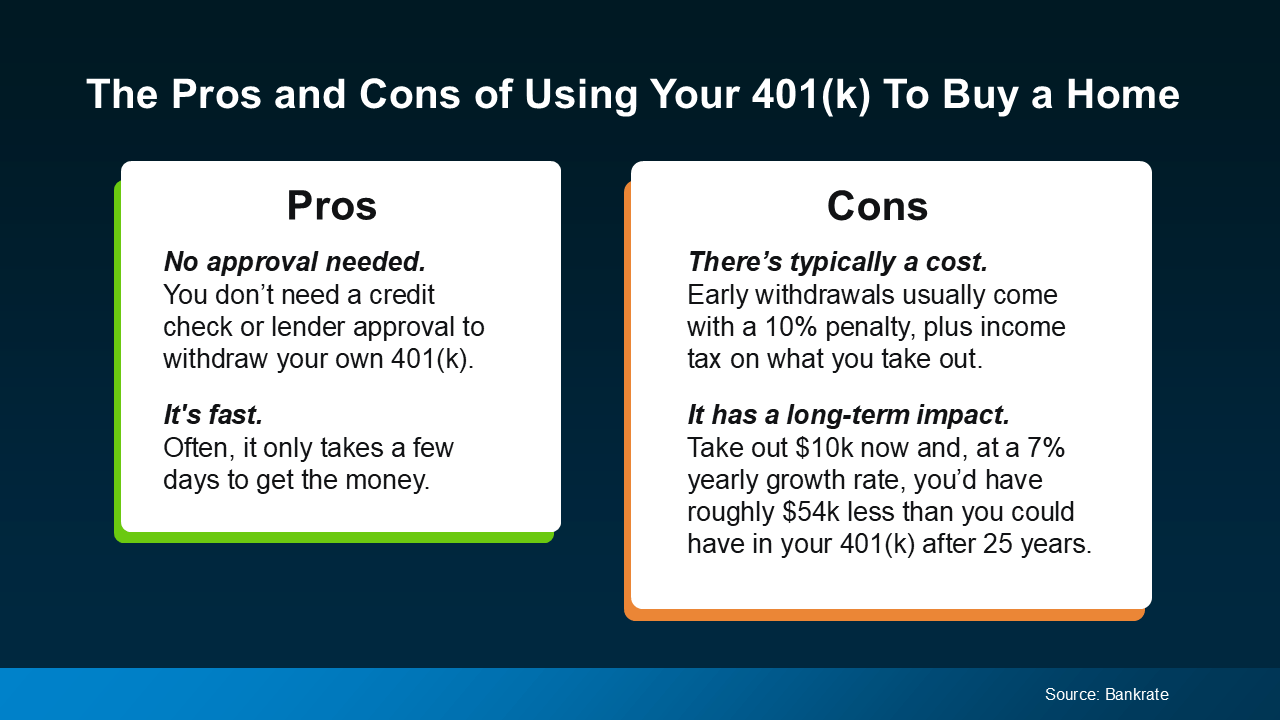
Taking money out now could affect your long-term investment growth. Depending on how the money is accessed, there may also be taxes, additional tax penalties, repayment requirements, or other consequences.
That is why it is important to understand exactly what you are considering before moving forward.
A 401(k) Loan and a Withdrawal Are Not the Same
The financial consequences can vary depending on how funds are accessed.
Some employer-sponsored retirement plans may allow participants to take a 401(k) loan. Others may allow certain types of withdrawals. Some plans may not offer either option.
A 401(k) loan generally involves borrowing against your account and repaying the money to your retirement account under the plan’s rules. If the loan meets IRS requirements and is repaid on schedule, the loan amount is generally not taxed when you receive it.
A withdrawal permanently removes money from your retirement account. Depending on your age, plan type, and the reason for the withdrawal, it may be taxable and could trigger an additional 10% tax penalty.
The IRS notes that early withdrawals from retirement accounts before age 59½ generally may be subject to an additional 10% tax unless a specific exception applies.
It is also important to know that using a 401(k) withdrawal to buy a home does not automatically qualify for a first-time homebuyer exception. That exception is commonly associated with certain IRA withdrawals, not traditional 401(k) withdrawals.
Whether a loan or withdrawal is available depends on your specific plan and financial circumstances.
That is why this is a conversation for your financial professional, not just your real estate agent.
Your real estate agent can help you understand the home-buying process and local market. Your financial, tax, or retirement professional can help you understand how accessing retirement funds may affect your broader financial plan.
Consider Other Options Before Using Retirement Savings
Your 401(k) may not be your only option for covering the upfront costs of buying a home.
Depending on your circumstances, you may want to explore the following options.
Low-Down-Payment Loan Programs
Some mortgage programs allow qualified buyers to purchase a home with a smaller down payment.
For example, FHA-insured financing may allow eligible borrowers to put down as little as 3.5%, depending on credit qualifications and applicable loan requirements.
Other loan programs may have different requirements, including options that may allow eligible buyers to purchase with little or no down payment.
A qualified lender can explain which programs may be available to you and how each option could affect your monthly payment, mortgage insurance, cash requirements, and overall costs.
Down Payment Assistance
There may also be down-payment and closing-cost assistance programs available to eligible buyers.
For example, Georgia Dream offers several programs for eligible Georgia homebuyers. Under current program information, the standard Georgia Dream option may provide assistance equal to 5% of the home’s purchase price, up to $10,000. The Georgia Dream PEN program may provide up to 6% of the purchase price, up to $12,500, for eligible public protectors, educators, healthcare providers, and active military members.
Program availability, income limits, purchase-price limits, lender requirements, and eligibility standards can change. Ask a qualified lender whether any current program may apply to your situation.
Eligible Gift Funds
Depending on the loan program and circumstances, some buyers may be able to use eligible gift funds toward certain home-buying costs.
Rules for gift funds vary by loan type. It is important to discuss the source, documentation, and allowable use of any gift funds with your lender before relying on them as part of your purchase plan.
Look at the Whole Picture
The biggest question is not simply:
“Can I use my 401(k) to buy a house?”
It is:
“Does using my retirement savings make sense for my overall financial situation?”
Before making a decision, consider the potential impact on:
Your retirement savings.
Long-term investment growth.
Taxes and possible penalties.
Loan repayment requirements.
Your monthly mortgage payment.
Your emergency savings.
Your other financial goals.
Your ability to handle unexpected homeownership expenses.
Buying a home is a major financial decision. It is important to evaluate the entire picture rather than focusing only on the amount needed for the down payment.
Your Local Market Is One Piece of the Puzzle
Here in Hinesville, Fort Stewart, and throughout Southeast Georgia, your real estate professional can help you understand what homes are available, how prices compare, and what purchasing strategies may be worth discussing.
But your financing strategy should also be developed with a qualified lender and financial professionals.
The right approach depends on your individual circumstances, financial goals, available loan options, and comfort level.
There is no single financing strategy that is right for every buyer.
Bottom Line
Using your 401(k) to help purchase a home may be an option worth discussing, but it should not be a decision made simply because you need additional funds for a down payment.
Before accessing retirement savings, take the time to understand the possible short-term and long-term consequences and explore other financing and assistance options.
If you are considering buying a home in Hinesville, Fort Stewart, or another Southeast Georgia community, The Shanken Team can help you understand the local real estate market and connect you with a qualified lender who can explain your home financing options.
Your financial advisor, tax professional, or retirement plan administrator can then help you determine whether accessing retirement savings fits into your overall financial plan.
The Shanken Team is committed to Equal Housing Opportunity and provides professional real estate services in accordance with federal, state, and local fair housing laws.